Wolfe Research Sees Wynn Al Marjan Exceeding $1.66bn Annual Gaming Revenue
Wolfe Research projects that Wynn Al Marjan Island could generate over $1.66 billion in annual gaming revenue once fully ramped, surpassing earlier estimates and positioning it among the world’s top integrated resorts. What this means for Ras Al Khaimah.
- Wolfe Research forecasts >$1.66bn annual gaming revenue for Wynn Al Marjan.
- Estimate exceeds previous consensus.
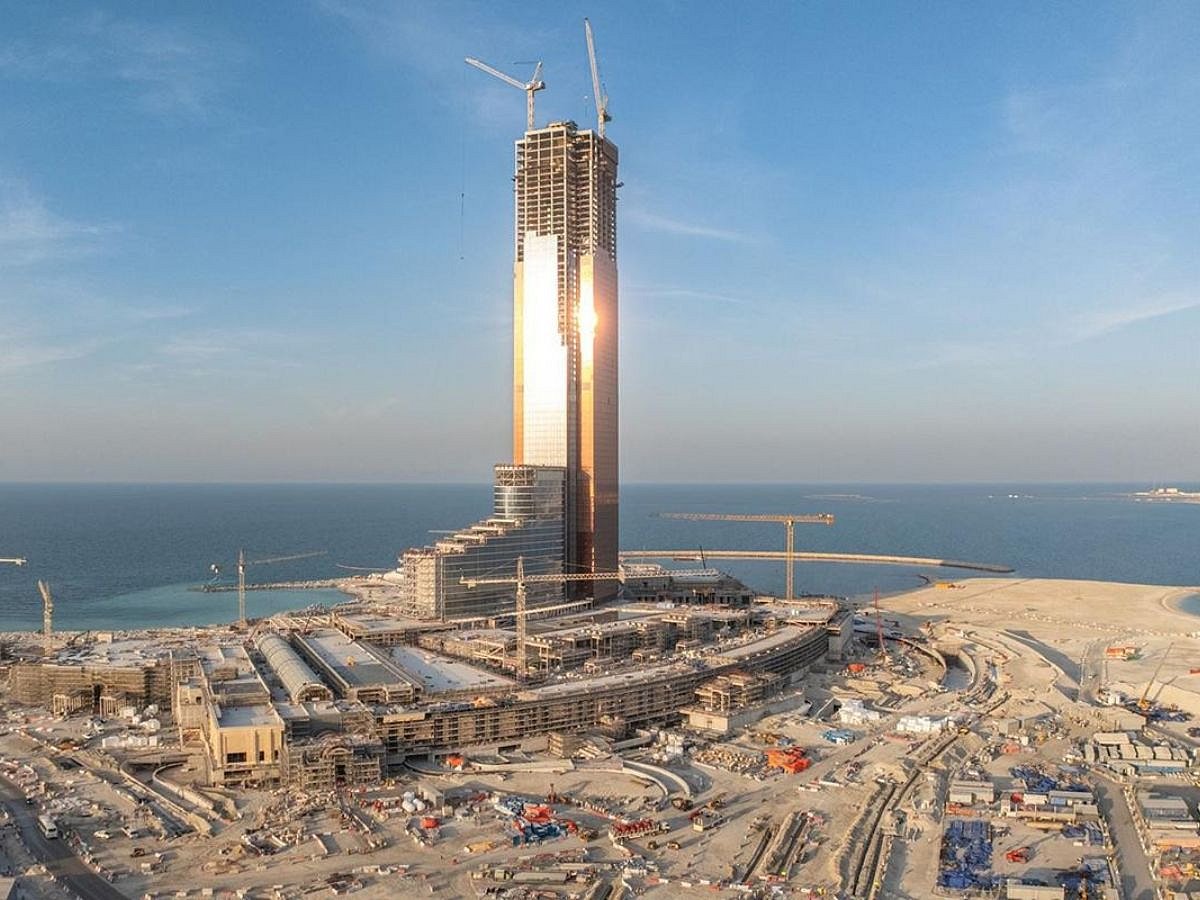
- Resort on track for 2027 opening with 1,542 keys and 98-berth marina.
- 2027 — Key year
- $1.66bn — Project value
- 12% — Notable rate
## What is Wolfe Research’s new forecast for Wynn Al Marjan Island’s gaming revenue? Equity research firm Wolfe Research has published a note projecting that Wynn Al Marjan Island, the UAE’s first integrated casino resort, could generate over $1.66 billion in annual gaming revenue at maturity (assumed FY2029), according to reports from SCCG Management and World Casino News. This exceeds the previous consensus estimate of $1.3-1.4 billion and would place the resort among the top 10 highest-grossing casino properties globally. The forecast assumes a 2027 opening, full ramp by year three, and a gaming tax rate of 12% on gross gaming revenue (GGR) as per the UAE’s federal gaming regulatory framework.
Wolfe’s model incorporates a Monte Carlo simulation of visitor volumes, average daily theoretical win per visitor, and table/slot mix. Key inputs include: 2.5 million annual visitors (60% international), 35% casino penetration rate, average theoretical win of $190 per gaming visitor, and a 60/40 slot-to-table ratio. The note highlights upside risk from premium mass and VIP segments, which are underpenetrated in the GCC compared to Macau or Singapore.
## What are the resort’s non-gaming revenue drivers? Beyond gaming, Wolfe estimates non-gaming revenue (rooms, F&B, retail, entertainment, marina) at $850 million annually at maturity, bringing total net revenue to ~$2.5 billion. The 98-berth superyacht marina (recently unveiled) targets the ultra-high-net-worth segment, with berth fees averaging $150,000/year. The resort’s 1,542 keys include 300 suites and villas, commanding ADR of $1,200+. F&B will feature 15+ outlets, including three Michelin-starred concepts. Retail comprises 80,000 sq ft of luxury boutiques. Entertainment includes a 3,000-seat theatre and a nightclub complex.
Construction remains on schedule: Wynn Resorts CEO Craig Billings recently stated that the Iran-Israel conflict in late 2024 cost only one day of construction, and the project is 62% complete as of September 2026. Total development cost is estimated at $4.2 billion.
## What are the implications for RAK’s gaming regulatory framework and investment case? The $1.66 billion GGR forecast implies ~$200 million in annual gaming tax revenue for the federal government, with a revenue-sharing agreement allocating a portion to RAK. This fiscal contribution strengthens the investment case for RAK’s infrastructure spend (airport, rail, utilities) supporting the resort. For investors, the forecast validates the GCC’s first-mover advantage in regulated gaming — a market Wolfe estimates could reach $5-7 billion GGR by 2030 if additional licences are awarded. However, risks include regulatory changes, geopolitical instability, and execution risk on the non-gaming amenities that drive length of stay and total wallet share.
Frequently asked
What is Wolfe Research’s gaming revenue forecast for Wynn Al Marjan at maturity?
Over $1.66 billion annual gaming revenue by FY2029.
What are the key assumptions behind the forecast?
2.5 million annual visitors, 35% casino penetration, $190 average theoretical win per gaming visitor, 60/40 slot-to-table ratio, 12% gaming tax rate.
What is the projected total net revenue including non-gaming?
Approximately $2.5 billion annually at maturity, with $850 million from non-gaming (rooms, F&B, retail, marina, entertainment).
InsideRAK is an independent publisher and is not affiliated with any Ras Al Khaimah government body. This report was compiled from the sources above and verified against published records. Spot an error? corrections@insiderak.com